Pay as little as ~3% tax on your IP income with the Cyprus IP Box.
The Cyprus IP Box can reduce tax to 3% on eligible net IP profit at full nexus. We help assess the asset, document development and prepare the tax position.
- Ebrovia Ltd · Paphos, Cyprus
- OECD-compliant
- Fixed-fee engagements
- Optional tax ruling support
~3%
Effective tax rate (2026)
80%
Deduction on qualifying IP profit
8
Website languages
21
Working days: expedited procedure, complete information required
What is the Cyprus IP Box?
The Cyprus IP Box is a special, fully legal tax discount for companies that make money from intellectual property — things like software you wrote or a patent you own.
For 2026 corporate examples: UE = min(30% × QE, A + R); OE = QE + A + R; N = min(1, (QE + UE) / OE). The deduction is 80% × OI × N. Taxable IP income is OI minus that deduction, not merely 20% of the nexus-adjusted portion. At 15%, the effective rate on OI is 15% × (1 − 80% × N).
It was introduced in 2012 and updated in 2016 to follow strict international (OECD) rules, so it is a stable, long-term tool — not a loophole. It lives in Article 9(1) of the Cyprus Income Tax Law.
Tax on €1,000,000 of IP profit
Illustration: eligible net IP income, full nexus and no other adjustments.
What the Cyprus IP Box gives you
Tap each feature to see the detail.
How the IP Box works
Four simple steps turn your IP profit into a ~3% effective tax rate.
- 1
IP income
€1,000,000
Illustration: eligible net IP income, full nexus and no other adjustments.
- 2
Deduct 80%
− €800,000
Treated as a tax-free expense
- 3
Tax the 20%
€200,000 × 15%
Only one-fifth is taxed
- 4
You pay
€30,000
≈ 3% effective rate
Work out your IP income
Take everything you earn from the qualifying IP (royalties, software fees, IP embedded in products) and subtract the direct costs of earning it. That is your net IP income.
Apply the nexus ratio
QE is qualifying R&D, A is acquisition cost and R is related-party R&D. OE = QE + A + R. UE = min(30% × QE, A + R). Nexus = min(1, (QE + UE) / OE), where OE is positive. Use the asset’s relevant historical expenditure; the denominator is not every accounting expense.
Calculate the IP deduction
Calculate the capped uplift and nexus fraction, then subtract the deduction from the full OI. The portion outside the nexus-adjusted profit remains taxable. A zero denominator does not establish full nexus.
Tax the remaining net income
For 2026 corporate examples: UE = min(30% × QE, A + R); OE = QE + A + R; N = min(1, (QE + UE) / OE). The deduction is 80% × OI × N. Taxable IP income is OI minus that deduction, not merely 20% of the nexus-adjusted portion. At 15%, the effective rate on OI is 15% × (1 − 80% × N).
The “nexus” rule
Cyprus only gives you the discount on the part of the IP that you genuinely developed.
QE is qualifying R&D, A is acquisition cost and R is related-party R&D. OE = QE + A + R. UE = min(30% × QE, A + R). Nexus = min(1, (QE + UE) / OE), where OE is positive. Use the asset’s relevant historical expenditure; the denominator is not every accounting expense.
QP = OI × min(1, (QE + UE) / OE); UE = min(0.30 × QE, A + R)
Your benefit is scaled by
Capped at 100%, with a positive denominator. QE: qualifying R&D; A: acquisition; R: related-party R&D. A zero denominator does not establish eligibility.
OI — Overall income
Net income from the qualifying IP, after the direct costs of earning it.
QE — Qualifying expenditure
R&D you do yourself or buy from unrelated parties.
UE — Uplift
A bonus of up to 30% of QE, capped at what you spent on acquisition + related-party R&D.
OE — Overall expenditure
Everything: QE plus IP you bought plus related-party R&D.
Cyprus IP Box tax calculator
Adjust the editable fields to match your case and see your approximate effective tax rate using the full OECD nexus formula at the 2026 corporate rate of 15%.
Overall income
Qualifying expenditure
Non-qualifying expenditure
Effective tax rate
3.0%
Indicative only — not tax advice. The formula is QP = OI × (QE + UE) / OE, capped at 100%. Actual results depend on your facts and documentation.
How your structure changes the rate
The same €1,000,000 of IP income — three different setups, three very different tax bills.
Internally developed IP
Optimal| Overall income (OI) | €1,000,000 |
|---|---|
| Internal R&D (QE) | €500,000 |
| Nexus ratio | 100% |
| Qualifying profit | €1,000,000 |
| 80% deduction | − €800,000 |
| Taxable profit | €200,000 |
Why this result
You built the IP yourself, so all of your spending is your own qualifying R&D. The nexus ratio is 100%, which means the entire €1,000,000 counts as qualifying profit. Cyprus then lets you deduct 80% of it (€800,000), leaving just €200,000 to be taxed at 15% — that's €30,000, or a 3.0% effective rate. This is the best outcome the regime allows.
Acquired IP + third-party R&D
Partial| Overall income (OI) | €1,000,000 |
|---|---|
| Acquisition cost | €300,000 |
| Unrelated-party R&D (QE) | €200,000 |
| Nexus ratio | 52% |
| Qualifying profit | €520,000 |
| 80% deduction | − €416,000 |
| Taxable profit | €584,000 |
Why this result
Here you bought the IP for €300,000 and only €200,000 of R&D was your own (done by an unrelated firm). The nexus formula only rewards R&D you funded: (€200,000 + €60,000 uplift) ÷ €500,000 total spend = 52%. So only €520,000 counts as qualifying profit. After the 80% deduction (€416,000), €584,000 is taxed at 15% = €87,600 — an 8.8% rate. The money you spent buying the IP dragged the ratio down.
Acquired IP + related-party R&D
No benefit| Overall income (OI) | €1,000,000 |
|---|---|
| Acquisition cost | €300,000 |
| Related-party R&D | €200,000 |
| Qualifying expenditure | €0 |
| Nexus ratio | 0% |
| Qualifying profit | €0 |
Why this result
Nothing here counts as your own qualifying R&D: you bought the IP (€300,000) and the R&D (€200,000) was done by a related company in your own group. Qualifying expenditure is therefore €0, the nexus ratio is 0%, and qualifying profit is €0. There is no deduction at all, so the full €1,000,000 is taxed at the normal 15% = €150,000. You get no IP Box benefit whatsoever.
At full nexus, eligible net IP profit can reach a 3% effective corporate tax rate in 2026. The result depends on qualifying rights, income and the asset’s documented R&D history; the location of developers alone does not determine eligibility.
Wondering what your effective rate would be?
Get a free, confidential assessment — we'll confirm if you qualify and quote a fixed fee, usually within one business day.
Key Cyprus IP Box concepts, explained
Tap any concept to expand a clear, plain-language explanation.
Which income qualifies?
The discount only applies to income that comes from your qualifying IP. Here is what is in — and what is out.
Royalties & licence fees Qualifies
A company pays you to use your patent or software.
Software subscriptions (SaaS) Qualifies
Monthly/annual fees customers pay to use software you wrote.
IP embedded in a product's price Qualifies
You sell a device and part of the price reflects your patented technology.
Compensation for the IP Qualifies
Insurance or damages you receive relating to the qualifying IP.
Brand / trademark licensing Excluded
Letting others use your brand name or logo — this is marketing IP, excluded.
General trading profit Excluded
Profit that has nothing to do with your IP — taxed at the normal 15%.
Where must your R&D come from?
Who does the research and development decides how much benefit you get. This is the part most people get wrong.
Your own in-house R&D team
Counts in full. This is the best case — it pushes your nexus ratio toward 100%.
Outsourced to unrelated third parties
Counts in full. An independent dev shop or lab abroad is fine.
Outsourced to related parties
Does NOT count. R&D bought from your own group/subsidiaries lowers the benefit.
Buying ready-made IP
Acquisition cost does NOT count as your R&D — it lowers the nexus ratio (but a 30% uplift softens this).
Which IP qualifies — and which doesn't
The rule of thumb: things you invent or create qualify; things you use to market a product do not.
Qualifies
- Patents (and patent extensions / SPCs)
- Copyrighted software
- Utility models
- Plant breeders' / genetic IP
- Orphan-drug designations
- Other certified novel, non-obvious, useful IP*
*Other IP qualifies only for smaller businesses — under €7.5m IP revenue (€50m group) — and must be certified as genuinely new.
Does not qualify
- Trademarks
- Brands / brand names
- Image rights
- Goodwill
- Other marketing intangibles
These are “marketing” IP — they help sell a product rather than being an invention.
You also need real substance & records
This is not a paper exercise. You must actually carry out R&D and keep clear records, kept up to date as you go — what was developed, who developed it, and how much each asset cost. These records prove your nexus ratio if the tax office asks. We set this up for you from day one.
You likely qualify if…
Check the taxpayer against regulation 6.
Establish the relevant ownership and qualifying asset.
Identify income and expenditure attributable to the asset.
Assess residence and permanent-establishment issues separately.
The steps to get your IP Box in place
We handle the whole journey — you focus on your business.
Assessment
Gather IP ownership and assignment records, customer contracts, historical R&D expenditure and the allocation of income and costs by asset. Identify the decision-makers and development functions. Unrelated overseas development is not automatically excluded; the regulations do not impose a universal local-developer requirement.
Structuring
The relief is claimed through the relevant tax computation and return when its conditions are met. A ruling does not switch the relief on. Track qualifying expenditure, income and changes annually, and assess the actual deduction for each period rather than assuming a permanent 3% rate.
Application & tax ruling
Preparation depends on ownership documents, expenditure records and the proposed structure. Circular 2016/13 provides an expedited 21-working-day procedure, subject to the necessary information being complete. Neither a positive ruling nor a fixed end-to-end completion date is guaranteed. Do not treat a commercial estimate of 3–6 months as a statutory standard-track deadline.
Ongoing compliance
Budget for accounting, tax filings, the applicable audit or review requirements, corporate administration and the actual operations needed by the business. The €350 annual company levy was abolished from 2024 onwards; earlier outstanding years remain separate. It must not be included as a recurring 2026 company levy.
Pricing & what's included
The published indicative professional fee is €5,000–€8,000 plus VAT. An optional ruling request has a separate government fee of €1,000 for the standard route or €2,000 for expedited handling. Company formation, if needed, starts from €799 plus VAT and actual expenses. Confirm the scope, exclusions and current charges in a written quote before engagement.
Our professional fee
€5,000 – €8,000+ VAT
Plus actual costs and the government fee shown opposite.
What this includes
- IP structuring — Correct structuring of the IP within your company to maximize compliance and tax efficiency.
- Detailed analysis & strategy — Full review of how your IP qualifies, with tailored guidance based on your business activities.
- Meetings & consultations — Ongoing discussions to align the application with your objectives and address concerns.
- Preparation & submission — An advance ruling is optional. It addresses the tax treatment of the facts disclosed; it does not independently verify those facts or approve every future transaction. Changes in the facts or law can affect reliance. A company must substantiate its claim and maintain records whether or not it requests a ruling.
Government fee — pick your speed
Government fee · timing depends on the case
Government fee · 21-working-day procedure, subject to complete information
All fees are exclusive of VAT and government fees.
Get a fixed quote → book a callNeed a Cyprus company too?
We also handle Cyprus company formation, so you can set up your company and structure your IP in one place.
from €799
+ VAT + actual expenses
Cyprus vs other EU IP boxes
Most EU countries have an IP discount. Cyprus has one of the lowest rates of all.
| Country | IP Box rate | Normal corporate rate |
|---|---|---|
| Cyprus | ~3% (2026) | 15% |
| Malta | 1.75% | 35% |
| Belgium | 3.75% | 25% |
| Luxembourg (Luxembourg City) | ~4.77% | 23.87% |
| Poland | 5% | 19% |
| Netherlands (Innovation Box) | 9% | 25.8% |
| Ireland (Knowledge Development Box) | 10% | 12.5% |
Rates indicative, from Tax Foundation Europe (2025), updated for Cyprus's 2026 reform. Cyprus also gives you EU membership, an English-friendly legal system and a wide tax-treaty network.
Beyond the rate — why founders choose Cyprus
Broad income scope
The benefit applies to a wide range of IP income — royalties, licence fees, software revenue and IP embedded in product sales — not just patents.
IP disposal: capital or trading?
Capital gains from selling qualifying IP are fully exempt where the disposal is capital in nature.
EU & OECD-compliant
An EU member state, with a regime built on the OECD BEPS Action 5 modified-nexus standard — stable and defensible.
Common-law system & treaties
An English-language, common-law-influenced legal system and an extensive network of double-tax treaties.
Your IP is protected worldwide
Cyprus has signed all the major international IP treaties, so rights registered here are recognised and enforceable around the globe.
A focused practice, built around one regime
Gather IP ownership and assignment records, customer contracts, historical R&D expenditure and the allocation of income and costs by asset. Identify the decision-makers and development functions. Unrelated overseas development is not automatically excluded; the regulations do not impose a universal local-developer requirement.
Specialists, not generalists
The IP Box regime is our core focus, not a sideline.
End to end
From the first eligibility check to the tax ruling and ongoing compliance.
OECD-compliant by design
Structures built to hold up under scrutiny — no shortcuts.
Transparent, fixed fees
You know the cost before you start.
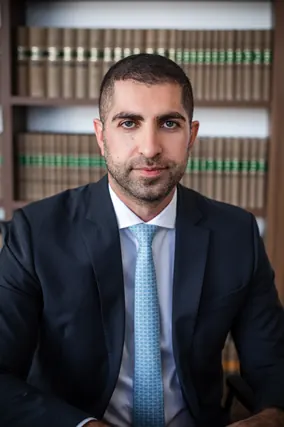
Gregoris Philippou
Founder & Principal
Gregoris Philippou leads IPBox Cyprus. A Cyprus advocate admitted to the Bar in 2013, he has built a distinguished career in corporate and commercial law, tax, and dispute resolution, and is regularly consulted on complex commercial and tax matters. He combines deep technical knowledge of the Cyprus tax framework with a practical, structuring-first approach — exactly what the IP Box regime demands.
Focus
Education
- LL.B. (First-Class) — University of Leicester (George Heim Memorial Trust Prize)
- LL.M. in Commercial Law — University of Cambridge (Cyprus Ministry of Education scholarship)
- Legal Practice Course (LPC) — BPP Law School
Memberships
- Cyprus Bar Association (since 2013)
- Accredited ADR Mediator & Mediation Advocate
- Member, Chartered Institute of Arbitrators
Languages: Greek · English
IPBox Cyprus editorial team · Ebrovia Ltd · Updated September 27, 2026.
In-depth Cyprus IP Box guides
Dedicated pages for the questions that need more detail.
Frequently asked questions
The Cyprus IP Box is a tax regime under Article 9(1) of the Income Tax Law that allows an 80% deduction on qualifying profits from intellectual property such as patents and copyrighted software. Only 20% is taxed, producing an effective rate as low as ~3% at the 2026 corporate rate of 15%.
See exactly what the Cyprus IP Box could save you.
Book a free, no-obligation assessment. We'll confirm whether you qualify, estimate your effective rate, and give you a fixed quote — confidentially, usually within one business day.
- Ebrovia Ltd · Paphos, Cyprus
- Confidential & no obligation
- ~1 business-day response
Sources & further reading
Related guides
- Cyprus IP Box Regime 2026: The Complete Guide
- Cyprus IP Box vs Other EU IP Boxes (2026 Comparison)
- The Cyprus IP Box for Startups: A Founder's Guide (2026)
- Does Software Qualify for the Cyprus IP Box? (2026 Guide)
- How the Cyprus IP Box is calculated: the nexus fraction explained (2026)
- How Much Does the Cyprus IP Box Cost? (2026)
- How Long Does the Cyprus IP Box Take? Timeline & the Tax Ruling (2026)
- Cyprus IP Box Requirements & Substance (2026)
- Cyprus IP Box versus Ireland KDB: eligibility, tax base and claim timing
- Cyprus Non-Dom Status & the 60-Day Rule Explained (2026)
- Cyprus corporate tax 2026 reform: what changed (and what it means for IP)
- Cyprus IP Holding Company: Structure & Tax (2026)
- Cyprus IP Box for AI and machine-learning businesses